Square Invoices: Invoice Maker

- 3.90K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on Square Invoices: Invoice Maker from Appgk
I first looked at Square Invoices: Invoice Maker as a practical business tool rather than something designed for casual household budgeting. That distinction matters. It can be useful when several people share responsibility for a small side business, a home-based service, or occasional client work, but it is not a general family finance app. Its job is to keep invoices, estimates, bills, expenses, and payments together in one business-focused workspace.
In my experience, the most convincing reason to try it is the reduction in small administrative gaps. A shared household may have one person doing the work, another answering messages, and someone else checking whether a customer has paid. Moving those tasks into one place can make coordination easier. The trade-off is that everyone using the same business account needs clear boundaries. This is a tool for organized collaboration, not a replacement for personal accounts, family controls, or a full accounting department.
How Square Invoices fits a shared household business
Imagine a couple running a weekend cleaning service from home. One person visits customers and records expenses, while the other prepares invoices in the evening and follows up on unpaid work. A third household member might occasionally help with estimates or enter a receipt. In that situation, the app’s focus on invoicing, estimates, expenses, and payments can provide a shared reference point instead of leaving information scattered across text messages, notebooks, and email threads.
I like this scenario because it shows where the app is genuinely useful: the household is acting as a small business team. The app is not being asked to manage grocery spending or divide rent. It is helping the people involved remember what service was offered, what amount was requested, which costs belong to the work, and whether money has arrived.
Best Parts of Square Invoices: Invoice Maker
Things to Keep in Mind About Square Invoices: Invoice Maker
A useful workflow is to create an estimate before agreeing to a larger job, then use the accepted scope as the basis for the invoice. That can reduce misunderstandings when a customer remembers a different price or assumes an extra task was included. I would still review every line before sending anything, especially when a family member entered the original details from a phone while another person handled the customer conversation.
For a household that sells handmade items or provides occasional tutoring, the same principle applies. The person closest to the customer can communicate the details, while the person more comfortable with administration can prepare the paperwork. That division works best when the household agrees on naming conventions and keeps business expenses separate from personal purchases.
News and Features Related to Square Invoices: Invoice Maker

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
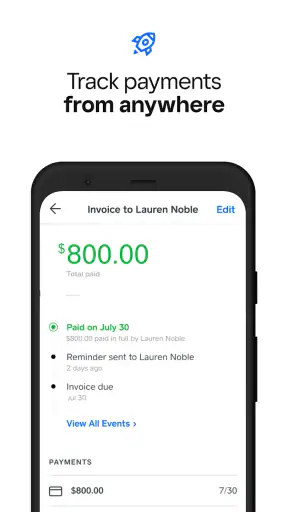
One non-obvious benefit is the value of a shared timeline of responsibility. If an invoice is prepared but payment has not been recorded, the next person taking over the work has a clearer starting point. Without that record, a family member may send a duplicate reminder or assume a customer is late when the payment was simply not noted.
What I would settle before installing it
Because this is a business app from Block, Inc., I would decide in advance who is responsible for the account, who is allowed to prepare documents, and who checks payments. Those decisions are more important than the installation itself. A shared phone can be convenient, but it also makes it easy for the wrong person to open or alter business information if the device is passed around casually.
Don't want to read the full review?
I would also avoid treating one shared login as a substitute for individual accountability. If several people use the same device or account, agree on a simple handoff routine: finish the current task, save the record, and tell the next person what still needs attention. The app can organize business information, but it cannot resolve confusion caused by unclear household roles.
Before sending the first invoice, I would prepare a small internal checklist. Confirm the customer name, service description, amount, due expectation, and the person who will handle follow-up. This sounds basic, yet it prevents the most common shared-use mistake: one person assumes another person checked the details.
Screenshots


I would also keep personal household purchases out of the business expense workflow. A receipt for supplies used for a client job belongs in the business process; a family grocery receipt does not simply because it was bought on the same phone. Mixing the two makes later review harder and can create unnecessary confusion when the household tries to understand its actual business costs.
Coordination is the real test
The app’s usefulness depends heavily on how well the household coordinates around it. I would not ask every family member to become an administrator. Instead, give each person a narrow responsibility. One person might collect job details, another might review estimates, and another might check whether payments were recorded. This keeps the app from becoming a dumping ground for half-finished entries.
A particularly helpful habit is to use a fixed review moment after each completed job. The person who did the work can confirm what was delivered and mention any extra materials. The person handling administration can then prepare or update the invoice. That short conversation is often more valuable than trying to reconstruct the job days later from memory.
For recurring household work, I would create a consistent description style. For example, use the same wording for a standard service and add a separate note for unusual work. Consistency makes old invoices easier to understand and helps the person handling follow-up recognize what a customer was charged for without asking the original worker every time.
Another practical tip is to separate “needs review” from “ready to send” in the household’s routine, even if that distinction is managed through conversation rather than a dedicated label. A draft prepared by a teenager helping with office work should be checked by the adult responsible for the business before it goes to a customer. That is not a criticism of the app; it is a sensible boundary for any shared financial tool.
When a customer pays, record it promptly and tell the other people involved. Otherwise, someone may continue chasing the payment. This is where a centralized record can help, but only if the household treats updates as part of the job rather than an optional afterthought.
Age, trust, and the limits of shared access
The app has an Everyone content rating, which makes it broadly approachable from an age-classification perspective. That should not be confused with unrestricted business responsibility. A younger household member may be perfectly capable of entering a customer name or checking a receipt, while still not being the right person to approve amounts, handle sensitive financial details, or send final documents.
I would use a supervised learning role for a child or teenager, such as organizing expense information or checking whether a job description is complete. The adult who owns the business should remain responsible for reviewing the result. This approach lets a young person learn how a small business operates without turning a shared device into an uncontrolled financial workspace.
Trust also matters between adults. If one person uses the app for a side business and another uses the same phone for personal tasks, make the boundary visible. Lock the device when appropriate, avoid leaving business screens open, and do not assume that being related removes the need for privacy. The app is about business records, and those records may include customer and payment information.
I would be especially careful in a household where several people share devices but do not share the same business role. The convenience of passing a phone across the kitchen can become a weakness if someone edits an entry without telling the account owner. A simple verbal rule—only the assigned person changes financial records—can prevent more trouble than a complicated process nobody follows.
For an older relative helping with invoicing, readability and confidence may matter more than the number of available tools. I would start with one task, such as reviewing an invoice before it is sent, rather than expecting that person to manage every part of the workflow immediately. The app is most effective when each user understands exactly what they are expected to do.
What the everyday workflow feels like
In a realistic evening routine, a household member returns from a job with a receipt for materials and a note about an extra service. The administrator opens the app, reviews the expense, checks the customer details, and prepares the invoice. Before sending it, both people confirm that the description matches the work. Later, when payment arrives, the record is updated so nobody sends an unnecessary reminder.
That process sounds simple, but it addresses a real weakness in informal businesses: the work is often remembered clearly while the paperwork is delayed. By the time someone sits down to invoice, the exact materials, agreed scope, or payment status may be unclear. Using one business-focused app encourages the household to capture those details closer to the moment they happen.
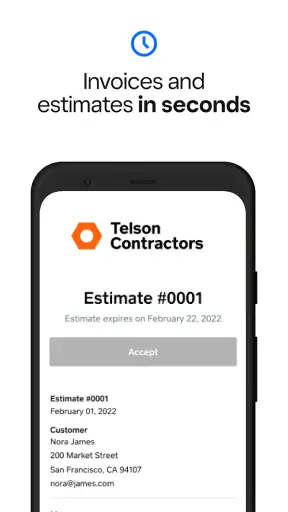
Estimates are particularly useful when the final cost is not obvious at the start. A household repair service, for example, may need to explain the expected work before committing to a final amount. I would use the estimate as a conversation tool, not merely as a form. If the customer changes the request, update the understanding before the work grows beyond the original expectation.
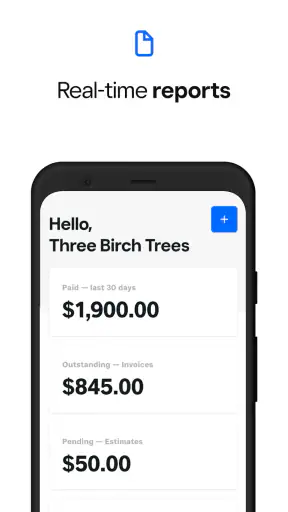
Expense tracking can also reveal whether a side business is actually worthwhile. A family may feel busy and assume the work is profitable, but regular purchases, travel-related costs, or replacement supplies can change the picture. Keeping those expenses visible gives the household a better basis for deciding which jobs are worth accepting.
One trade-off is that a focused invoicing app may feel too narrow for a business that has grown beyond basic billing. If you need deep inventory management, detailed payroll, extensive project planning, or complex accounting reports, you may eventually prefer a broader business platform. I would not choose this app simply because a household has many financial tasks; I would choose it when invoicing and payment coordination are the main problem.
Where it stands against familiar alternatives
The usual alternative for a very small household business is a spreadsheet combined with email, messaging, and a payment record kept somewhere else. That approach costs little and offers flexibility, but it depends on careful manual formatting and disciplined version control. In comparison, Square Invoices: Invoice Maker is more purpose-built for the movement from estimate to invoice to payment tracking.
A spreadsheet can still be better when the household wants custom calculations, unusual reporting, or a completely offline planning system. It may also feel more transparent to someone who wants to see every formula. The downside is that a spreadsheet does not naturally solve the problem of sending consistent business documents or keeping the workflow understandable for the next family member.
Another alternative is a full accounting package. That is the stronger choice for a growing company with several financial categories, formal bookkeeping needs, or a requirement to connect many parts of operations. For a home-based service that mainly needs clear invoices, expense records, estimates, and payment follow-up, a larger system may introduce more complexity than value.
Paper forms remain workable for someone with only a few customers, but they become awkward when several people need the same information. A paper invoice can be misplaced, and a handwritten note about payment may never reach the person doing follow-up. The app’s central appeal is not that it makes business magically simple; it gives a household a more consistent place to keep the process together.
Its average rating is 4.7 from around 20 thousand ratings, and the app has passed one million installs. Those figures suggest that it has found a broad audience, but they should not replace a fit assessment. A popular business app can still be wrong for a household that needs advanced accounting or wants to keep all financial activity entirely separate from a shared device.
Practical details before making it part of the routine
The app is free to install, with in-app purchases listed at twenty dollars per item. I would check the exact cost of any paid action before building the household’s process around it. “Free” makes it easy to start experimenting, but a business should understand which parts of its regular workflow may involve additional spending.
The current version is 7.22.1, and it requires an operating system version 9 or newer. That makes the device check straightforward: confirm the phone or tablet meets that requirement before assigning it to a family member. If the household relies on an older device, compatibility should be settled before moving records into a new workflow.
I would also test the routine with a small number of internal examples first. Create a sample estimate, review how the invoice is prepared, enter a representative expense, and practice marking a payment. The point is not to fill the account with fake business history; it is to make sure everyone understands the sequence and knows who reviews each step.
For a shared device, keep notifications and screen visibility in mind. A person using the phone for school, entertainment, or personal messages may not be the intended audience for business reminders. I would establish a habit of checking business updates during an agreed time rather than allowing them to interrupt every household activity.
The developer is Block, Inc., and the app belongs to the business category. That positioning is clear in daily use: the experience is centered on commercial tasks rather than household money management. If your main question is “Who owes the family for dinner?” this is not the tool I would reach for. If the question is “What did we quote, invoice, spend, and receive for this customer?” it is much more relevant.
Who should use it, and who should look elsewhere
I would recommend it to a freelancer, couple, parent-and-adult-child team, or small household partnership that needs a shared way to handle customer billing. It is especially suitable when the business has straightforward services, a modest number of moving parts, and a recurring need to turn completed work into understandable invoices.
I would also consider it for a person who works alone but wants a clearer separation between customer records and personal notes. Even without shared use, the focused workflow can be easier to maintain than a collection of documents and reminders. The benefits become stronger when another trusted person occasionally helps with administrative work.
I would skip it as the central system for a larger operation with complex bookkeeping, detailed stock control, formal staff management, or demanding financial analysis. I would also skip it for a family seeking parental controls, separate child profiles, allowance tracking, or a household budget dashboard. Those are different needs, and this app’s business focus does not make it a family-management platform.
One more exception is a household with no agreement about who owns the business records. If every person edits whatever they see, no invoicing app will provide reliable coordination. Establish responsibility first, then use the app to support that arrangement.
My household verdict
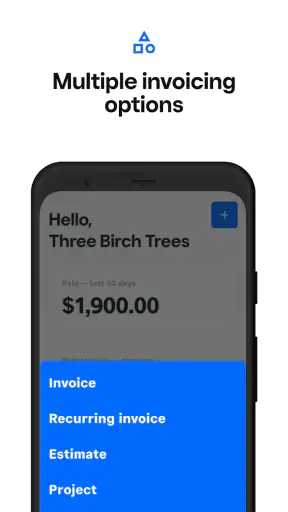
After looking at it through the lens of shared-device use, I see Square Invoices: Invoice Maker as a sensible tool for a household that is genuinely operating a small business together. Its strongest contribution is structure: estimates, invoices, expenses, and payment follow-up can become part of one repeatable routine instead of a series of improvised conversations.
I would recommend starting with clear account boundaries, a named reviewer, and a short handoff process. Let the person closest to the customer provide the job details, let the administrator prepare the paperwork, and make sure one responsible adult checks the final information. That approach gets more value from the app while limiting the risks of casual shared access.
My final opinion is positive but specific. This is not a universal money app, and it should not be presented as one. For a small household business that needs practical invoicing and payment organization, it can remove a lot of everyday friction. For personal family finances or a business that has outgrown basic billing, I would choose a different category of tool. Used within its proper boundaries, though, it is a focused and approachable option, available for free, with an Everyone age rating and a clear purpose from the moment you open it.
Square Invoices: Invoice Maker FAQ
What is Square Invoices: Invoice Maker used for?
Square Invoices: Invoice Maker is designed to help freelancers, independent professionals, and small businesses create and manage invoices from a mobile device. You can prepare professional invoices, add customer and business details, include products or services, set payment terms, send invoices, and monitor their status. It is especially useful for users who want to handle billing without relying on complicated accounting software.
Can I create and send professional invoices from the app?
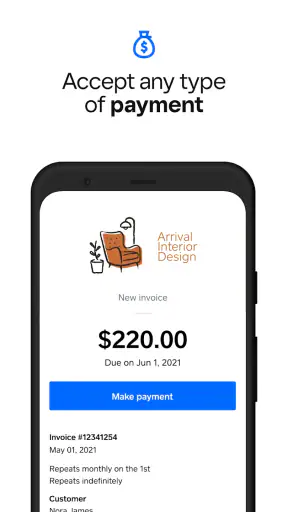
Yes. The app lets you build invoices by entering your business information, customer details, descriptions, quantities, prices, taxes, discounts, and payment due dates. After reviewing the information, you can send the invoice to your customer electronically. Templates and organized layouts make the finished document look more professional, although the exact customization options may depend on your Square account, region, and current app version.
Can customers pay invoices through Square Invoices?
Customers can generally pay eligible Square invoices using the payment methods made available by the business, such as cards or other supported options. The payment experience is handled through Square’s payment system, which can make it easier to track whether an invoice is unpaid, partially paid, or completed. Payment availability, processing fees, currencies, and supported methods vary by country and account settings.
Is Square Invoices: Invoice Maker free to download and use?
The app may be available to download without an upfront charge, but using Square’s invoicing and payment services can involve transaction or service fees. These costs may differ according to the payment method, location, account type, and features used. Before sending invoices or accepting payments, review Square’s current pricing information carefully, since downloading the app does not necessarily mean every feature is free.
Do I need a Square account to use Square Invoices: Invoice Maker?
A Square account is typically required to create invoices through Square’s platform and use features connected with payment processing, customer records, and invoice tracking. During setup, you may need to provide business and personal information for account verification. Availability can vary depending on your country and business category, so it is worth confirming that Square supports your location before downloading and completing the registration process.